Can Homeowners Insurance Deny a Roof Claim Because of Age?
Not for age alone, but age can shrink your payout or lead to a denial on other grounds. Texas draws a line between underwriting (whether you get coverage) and claims (what the policy pays after damage).
What the New Texas Rule Covers
On September 29, 2026, the Texas Department of Insurance clarified that insurers can’t decline or refuse to renew a homeowners policy based solely on the age of a house or its components, including the roof. Insurers may still consider physical condition. That rule governs coverage decisions. It doesn’t change how a claim is paid once you have a policy.
Where Age Still Affects Claims
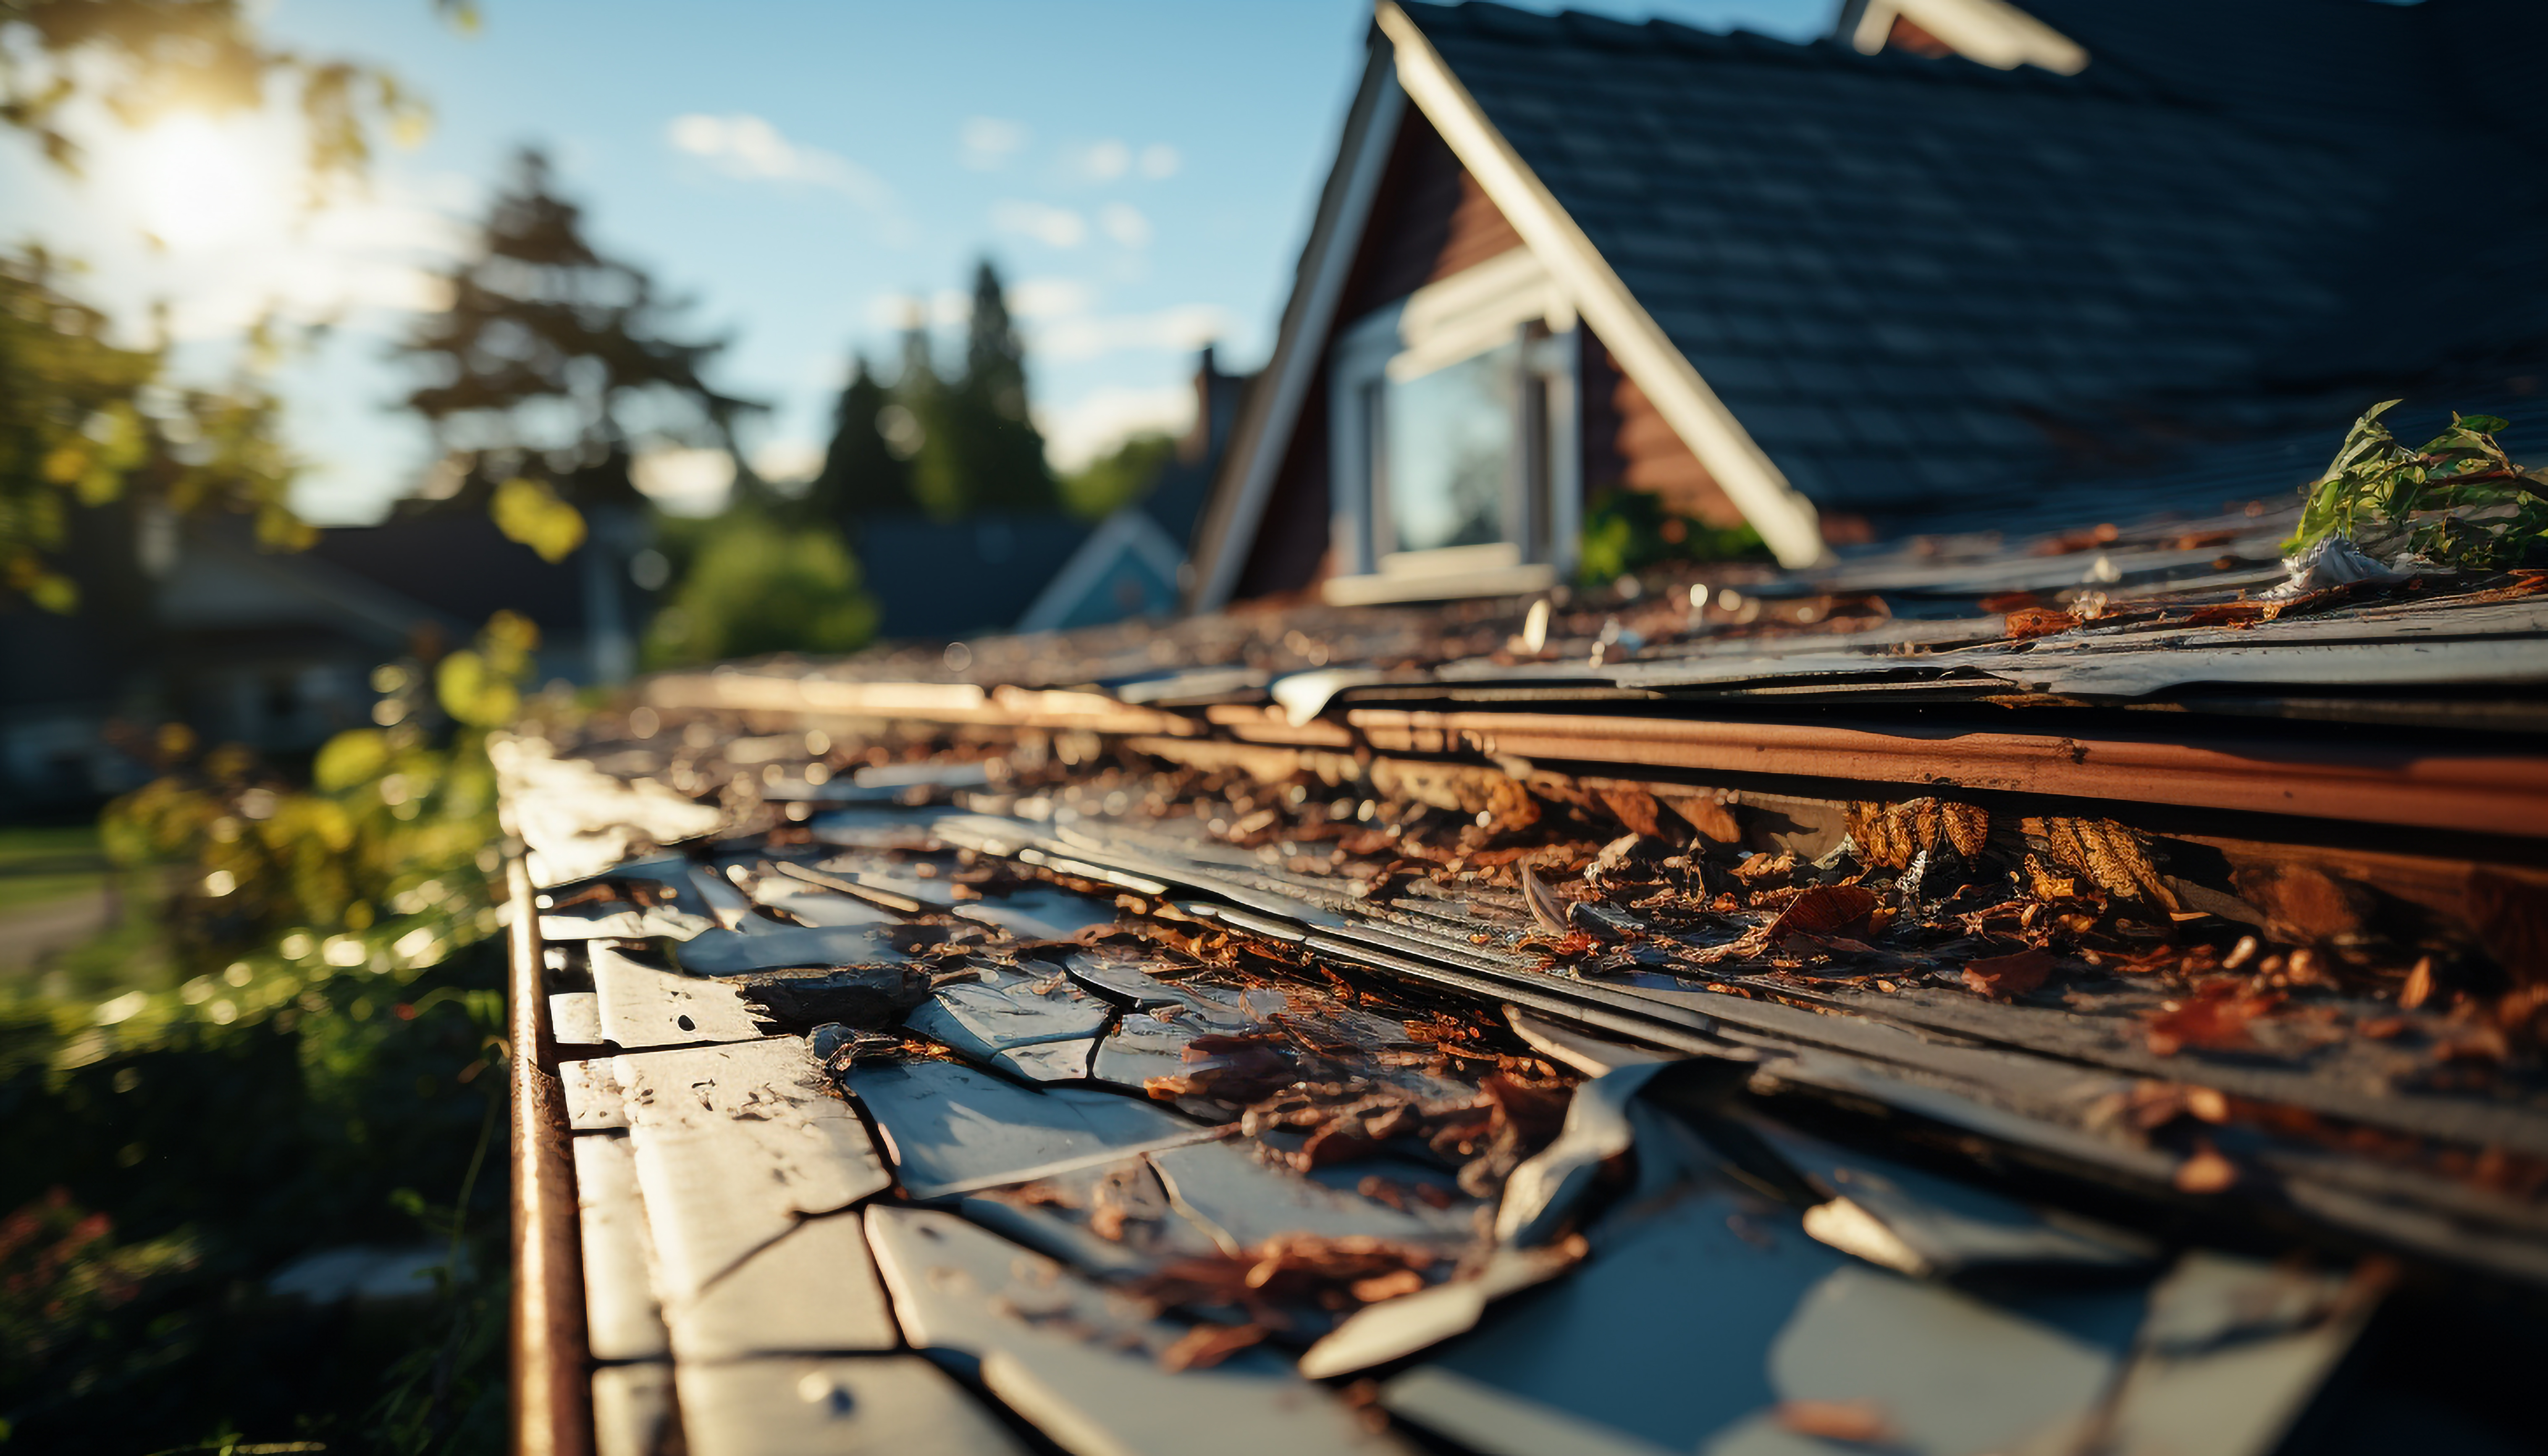
Wear and tear. Policies cover sudden damage from events like hail, wind, or a fallen tree, but not gradual deterioration. If an adjuster concludes that curling, cracking, or granule loss comes from age rather than a storm, the claim can be denied on that basis. Storm damage to an older roof is still generally covered, so a denial that blames age without a real inspection is worth challenging.
ACV payment. Many Texas policies switch roofs to actual cash value once they reach a certain age, often 10 to 15 years, sometimes through a roof payment schedule. ACV pays replacement cost minus depreciation. In some cases, depreciation on an old roof plus a percentage-based wind and hail deductible can leave you with little or nothing, even though the claim is technically covered.
How to Find Out What Applies to You
Look in your policy for sections called “Roof Surfacing Payment Schedule,” “Roof Surfacing,” or “Functional Replacement Cost.” Check your renewal documents each year, since a roof can move to ACV over time. Verify that the roof age your insurer has on file is correct, because errors can affect how depreciation is calculated.
If You Think a Denial Is Unfair
Request the denial in writing with the specific policy language. Ask for the adjuster’s photos and estimate. Get an independent roof inspection, ideally documenting storm damage with dated photos and weather records. Then you can request reinspection, invoke the appraisal clause for amount disputes, or file a complaint with TDI.
A Practical Takeaway
A roof’s age doesn’t automatically bar a claim in Texas, but it can limit what you collect. Run the numbers before filing, and consider how a roof replacement might restore replacement-cost coverage. TDI’s help line is 800-252-3439.